
Banks love boxes they understand, and a tiny house is not one of them. Too small for most mortgages, too house-like for some RV lenders, too mobile for construction loans — tiny house financing falls through the cracks between lending categories, and buyers usually discover that at the worst possible moment: after they have fallen for a house. This guide maps every viable funding path before that happens.
How to Finance a Tiny House: At a Glance
Learning how to finance a tiny house starts with accepting that there is no single “tiny house loan.” There is a maze of neighbouring products — RV loans, personal loans, construction-to-permanent loans, home equity, builder financing, chattel loans and creative routes like seller financing — each built for a different kind of house and a different kind of borrower. The cheapest money you can actually qualify for depends on three things: whether the house sits on wheels or a foundation, whether it carries recognised certification, and how strong your credit file is. The table below maps all ten parts of the maze covered in this guide, with the headline numbers for each path, so you can see at a glance which doors are realistically open to you before we walk through them one by one.
| Financing Path | Best For | Key Numbers |
|---|---|---|
| 1. RV Loans | RVIA-certified tiny houses on wheels from recognised builders | 7–12% APR · 5–15 year terms · $25,000–$150,000 |
| 2. Personal Loans | DIY builds, used purchases and funding gaps | 6–36% APR · 2–7 year terms · $5,000–$100,000 |
| 3. Construction-to-Permanent | Foundation builds on owned land | Mortgage rates · 15–30 year terms |
| 4. HELOCs & Home Equity | Borrowers who already own conventional real estate | Rates near mortgage rates |
| 5. Builder & Dealer Financing | One-stop purchase convenience | Often 2–4 points above market |
| 6. Chattel Loans | Tiny houses on wheels that RV lenders declined | 8–14% APR · 10–20 year terms |
| 7. Creative Paths | Used buys and patient, cash-staged builders | Seller notes at 8–12% over 3–7 years |
| 8. What Lenders Check | Every applicant, on every product | 650+ credit · DTI under 43% · 10–20% down |
| 9. The True Cost of Borrowing | Anyone choosing between rate and term | $80,000 borrowed four different ways |
| 10. The Financing Action Plan | Buyers 12 months out from purchase | Pre-approval 3 months before buying |
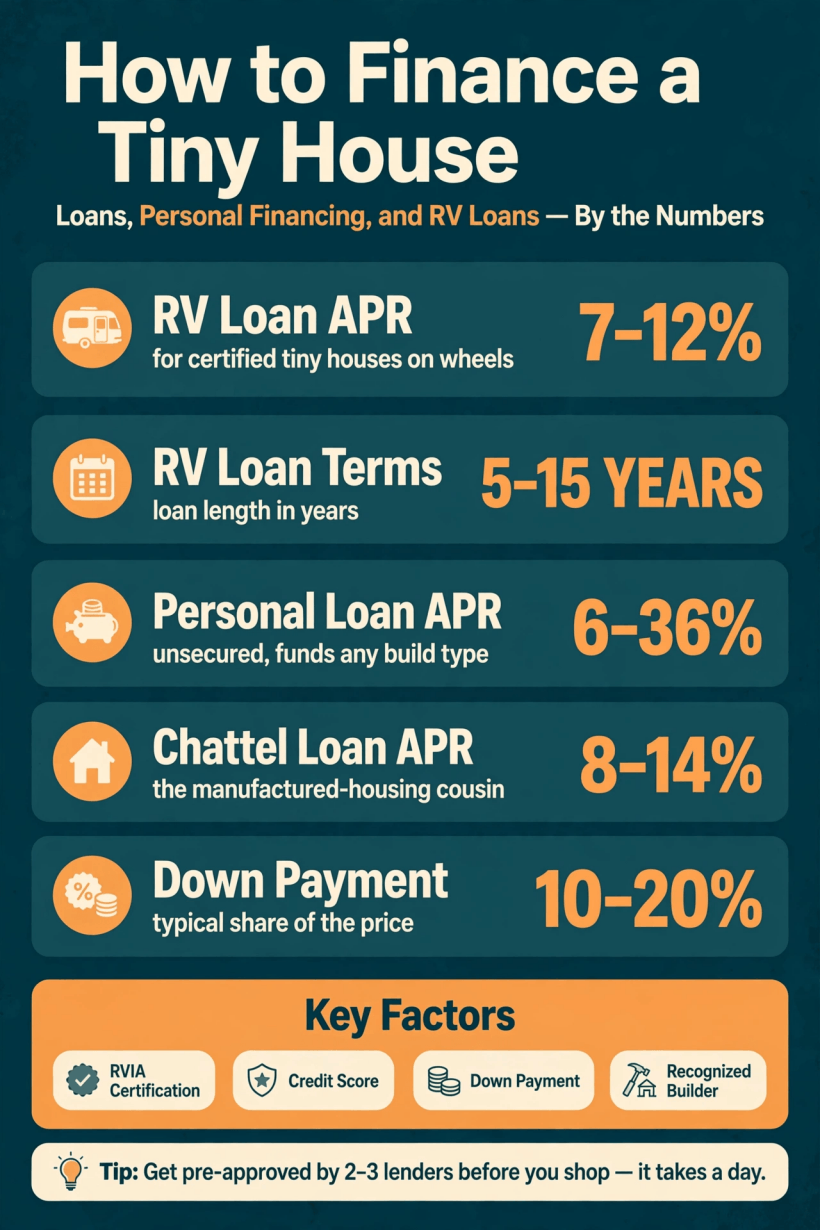
The maze at a glance: RV loans price at 7–12% APR over 5–15 years, unsecured personal loans run 6–36%, chattel loans sit at 8–14%, and most secured products expect 10–20% down.
1. RV Loans: The Default for Tiny Houses on Wheels
For an RVIA-certified tiny house on wheels, the RV loan is the standard product, and it is where most wheeled-tiny-house buyers end up. Terms run 5–15 years on amounts of $25,000–$150,000, with rates currently at 7–12% APR depending on credit and term. Lenders treat the house as a recreational vehicle, which is exactly why the pricing sits above mortgage rates: the loan is underwritten like an RV loan, not like a home loan. Qualification typically means a credit score of 650 or higher, a down payment of 10–20%, and RVIA certification, which is non-negotiable for most lenders. Just as important, the house must come from a recognised manufacturer — most lenders will not finance DIY builds through this channel at all.
Two practical moves sharpen this path. First, shop the lender, not just the loan: credit unions consistently beat national banks on RV loan rates for tiny houses, so a local credit union deserves a place on every shortlist. Second, get pre-approved by two or three lenders — a local credit union, a national RV lender and your own bank. Pre-approval takes about a day, and it transforms you from a dreamer into a buyer in a seller’s eyes. Because certification is the gatekeeper here, it also pays to understand the paperwork behind it before you apply; our guide to registering a tiny house as an RV walks through the DMV registration and certification steps that sit behind an RV lender’s checklist.
2. Personal Loans: Fast, Flexible, Expensive
Unsecured personal loans are the duct tape of tiny house finance: they fund almost anything, including the houses no other product will touch. Amounts run $5,000–$100,000 at 6–36% APR over 2–7 year terms. Because there is no collateral requirement, the money can fund a DIY build, a used purchase, or simply the gap between your savings and the asking price, and funding can arrive in days rather than weeks. For buyers whose project does not fit any secured category — above all self-builders, who should first weigh up whether to build their own tiny house — a personal loan is often the only mainstream door that opens at all.
The cost of that flexibility is real, and it shows up in the monthly payment. Rates sit far above secured lending, and the short terms compress repayment brutally: a $50,000 loan over 3 years at 12% costs $1,500 or more per month. That arithmetic is why the original guidance still stands — use personal loans for bridges and gaps, not for the whole house, whenever an alternative exists. A personal loan that covers a deposit while a cheaper product processes, or that tops up savings to reach a price, is a tool. A personal loan carrying an entire build at the top of its APR range is a burden that follows you into the house.
3. Construction-to-Permanent Loans: For Foundation Builds
Put the tiny house on a permanent foundation, build it to code on land you own, and the financing picture changes completely. That house can qualify for a construction loan that converts into a conventional mortgage — the cheapest money available anywhere in this guide, at mortgage rates over 15–30 year terms. The requirements are the mortgage world’s usual ones: owned land (or land purchased within the same transaction), a licensed builder or an approved owner-builder arrangement, code-compliant plans, and an appraisal that supports the value. In exchange for meeting them, the foundation builder borrows like any other homeowner.
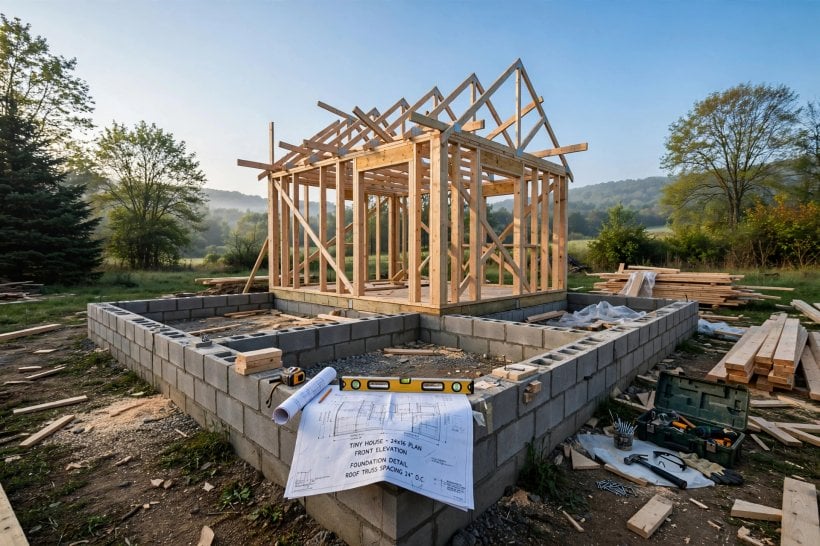
The catch is scale. Most lenders set minimum loan amounts of $50,000–100,000, and a $60,000 tiny house barely clears that bar — the loan can be too small for the product designed to fund it. This is where lender choice matters again: local and regional banks are far more flexible than national lenders on small construction loans, and they are used to judging the project in front of them rather than a category on a spreadsheet. Because the whole path depends on owning the right parcel first, it pairs naturally with doing the land homework early — our guide to where to buy tiny house lots covers how to find land that a lender, and a foundation build, can actually work with.
4. HELOCs and Home Equity Loans
If you already own conventional real estate, the cheapest tiny house financing available to you may be sitting inside your existing home. A home equity line of credit or a home equity loan borrows against that property at rates near mortgage rates, and the interest is potentially tax-deductible. The strategy is simple: draw on the equity in the house you have to fund the tiny house you want, whether it will serve as a primary residence, an accessory dwelling unit in the garden, or an investment. No certification maze, no minimum-loan problem, no RV underwriting — the existing property does the persuading.
The risk deserves equal billing with the rate. Your existing home secures the loan, so a default threatens both properties at once — the roof you live under now and the tiny roof you borrowed to build. That makes this path one for borrowers with stable equity and stable income, who can service the payment comfortably in a bad year as well as a good one. Used with that discipline, home equity is often the lowest-cost route in this entire guide. Used casually, it converts a small-house dream into a two-house liability.
5. Builder and Dealer Financing
Many tiny house builders offer in-house financing or partnered lending, and its appeal is obvious: one-stop shopping, with approval wrapped into the purchase itself. For a buyer tired of the category maze, signing once and driving away feels like the maze solved. Sometimes it genuinely is the practical option — a builder’s partner lender understands tiny houses in a way a high-street bank may not, and the process is fast because the paperwork was designed for exactly this product.
Convenience, though, has a price, and here it is measurable: builder financing often prices 2–4 points above market. The discipline is to treat it as a convenience option and a negotiating baseline, never as a default. Get an outside quote before signing — from the credit union, the RV lender, your own bank — and compare it line by line against the builder’s offer. That 30 minutes of comparison shopping routinely saves $5,000 or more in interest over the life of the loan. If the builder’s number wins honestly, sign it with confidence. If it does not, you have just been paid very well for half an hour’s work.
6. Chattel Loans: The Manufactured-Housing Cousin
Chattel loans are the niche most tiny house buyers have never heard of, and the one that rescues some deals. A chattel loan is a personal-property loan of the kind long used for manufactured homes: it is secured by the house itself rather than by real estate, with terms of 10–20 years and rates of 8–14%. Fewer lenders offer chattel loans for tiny houses specifically, but manufactured-housing lenders operate the closest existing industry, with underwriting habits built for homes that are personal property rather than land-tied assets.
The moment to explore this path is when the RV loan door closes. RV lenders usually decline over certification or builder-recognition issues — the house is well built but lacks the exact credentials that product demands. A chattel lender, judging the house as manufactured housing rather than as a recreational vehicle, may reach a different answer on the same application. Rates sit above RV loans and terms run longer, so it is rarely the first choice; but as a fallback that keeps a purchase alive, it belongs in every wheeled-house buyer’s back pocket.
7. Crowdfunding, Community Lending, and Creative Paths
Beyond the formal products sits a set of documented creative paths, each with real tiny house purchases behind it. Community lending circles are informal and relationship-based, pooling trust instead of collateral. Seller financing, where the seller carries the note, is common for used tiny houses on wheels and for land. Retirement account loans — borrowing from your own 401(k) — mean paying the interest to yourself, though the money leaves the market while it is borrowed. And build-in-stages funds each phase of a build in cash: the slowest path in this guide, and the cheapest, because no interest is paid to anyone.
Seller financing is the most structured of these, and its typical shape is worth knowing precisely: on a used tiny house on wheels, expect 20–30% down, a note of 3–7 years, interest at 8–12%, and a UCC lien filing on the house, with an attorney drafting the documents for $300–500. That last detail generalises to every creative path: each one needs paperwork. A proper promissory note and lien protect both sides of a friendly deal, and handshake loans destroy friendships. Creativity in financing is welcome; informality in documenting it is not.
8. What Lenders Actually Check
Across all of these products, lenders are evaluating the same short list. Credit score comes first: 700 or above unlocks the best rates, 650-plus is the practical minimum, and below 620 you should expect denials. Debt-to-income ratio comes next, with under 43% required for most products. Then the down payment — 10–20% is standard, and more down reliably means better rates. Finally, the house itself is checked: RVIA certification for homes on wheels, code compliance for foundation builds, and builder legitimacy, since most secured products will only finance recognised manufacturers.
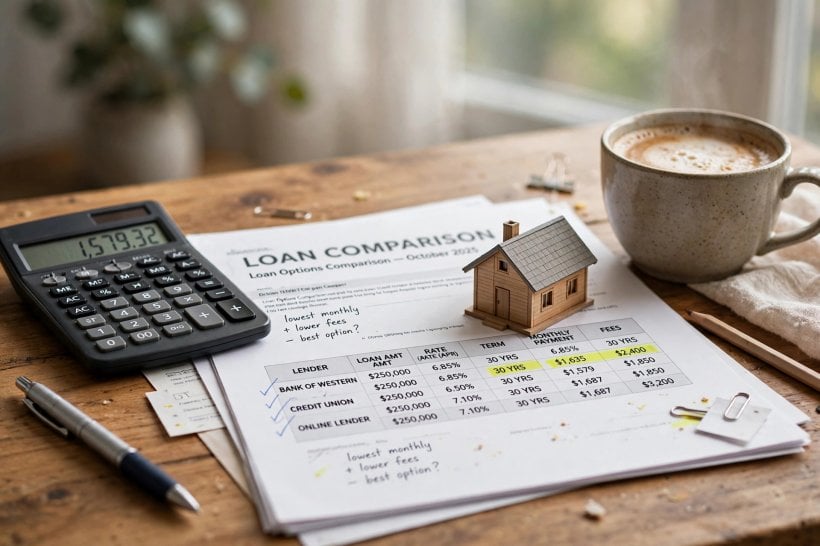
Read that checklist backwards and the DIY problem explains itself. A self-built house typically fails the last two checks — no certification, no recognised manufacturer — regardless of how well it is built or how strong the borrower’s credit is. That is why DIY is overwhelmingly cash-funded, sometimes topped up with the unsecured personal loans from section two. Knowing the checklist a year ahead is the whole game: every item on it — score, ratio, deposit, certification — can be improved or chosen deliberately, but almost none of them can be fixed in the week you find the house.
9. The True Cost of Borrowing: A Comparison
Rates and terms only become real when they are turned into monthly payments and total interest, so here is the same borrowing decision priced four ways, using the original worked examples. An $80,000 RV loan at 10% over 10 years costs $1,057 per month and $46,900 in total interest. Stretch the same $80,000 RV loan to 8% over 15 years and the payment falls to $765 per month, but total interest climbs to $57,600. Put $80,000 on a mortgage at 6.5% over 30 years — the foundation build’s privilege — and the payment drops to $506 per month, the lowest here, while total interest balloons to $102,000. And a $40,000 personal loan at 12% over 5 years costs $890 per month with $13,400 in total interest.
The lesson hides in the contrast between the second and third lines: the cheapest monthly payment is not the cheapest loan. The 30-year mortgage feels gentlest and costs the most; the shorter RV loan stings monthly and finishes far ahead on total cost. As a working rule, the shortest acceptable term at the lowest rate wins on total cost — acceptable being the operative word, because a payment you cannot sustain is no bargain at any rate. Before running your own version of this comparison, it helps to anchor the loan amount itself in reality by checking how much a tiny house costs across build types, so the figure you are financing is the figure the house will actually reach.
10. The Financing Action Plan
Good financing is mostly timing, so here is the plan in calendar form. Twelve months out: check your credit reports, pay down revolving debt, and save the down payment — this is when the lender’s checklist from section eight is cheapest to fix. Six months out: decide the house type, because wheels versus foundation determines the entire loan universe you will be shopping in. Three months out: get pre-approved by two or three lenders, and confirm the RVIA or certification requirements your chosen product demands, so no surprise surfaces after you have found the house.
At purchase, compare the builder’s financing offer against your pre-approvals and negotiate the rate, not just the price — a point off the rate can be worth more than a discount off the sticker. This is the moment where knowing how to finance a tiny house stops being research and becomes money. After purchase, set up autopay so no payment is ever late, and plan extra principal payments where the budget allows: tiny balances repay fast, and every early dollar of principal is interest that never accrues. Buyers who want the purchase process itself mapped end to end can follow it in our guide on how to buy a tiny house, which picks up where this financing plan hands over.
Final Considerations
Tiny house financing rewards preparation above all else. The borrower who arrives with good credit, a saved down payment, pre-approvals in hand and an RVIA-certified house from a recognised builder gets the best rates with the least friction — not because lenders are generous, but because every item on their checklist has already been answered. Every shortcut runs the other way: no certification, an unknown builder or weak credit each cost points on the rate, or close doors entirely. None of that is fixable at the sales desk, and all of it is fixable a year earlier.
Two habits tie the whole maze together. First, treat legality and paperwork as part of financing, not as separate chores — state rules shape which products even exist for your purchase, as the state-level walkthrough in our guide to buying a tiny house in Alabama shows in detail. Second, protect the asset the loan bought: once the financing closes, the house needs cover that matches how it sits, and our tiny house insurance guide for wheels versus foundation explains how that cover differs between the two worlds this guide has moved between. Finance the house like the significant purchase it is, and the monthly payment stays as small as the house.

11 Comments