

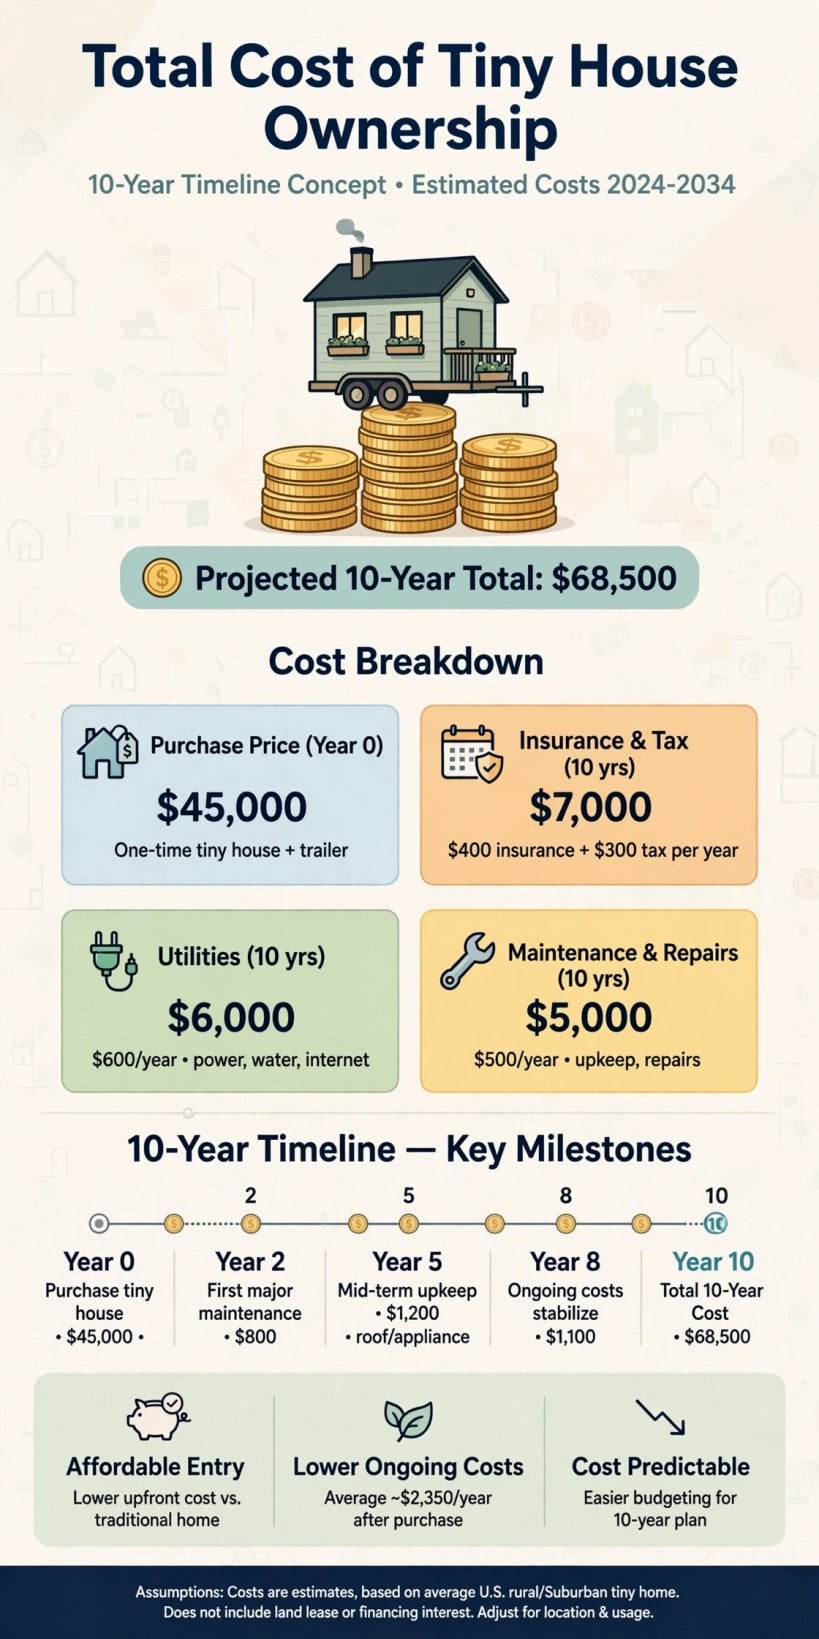
How much do tiny houses cost? The complete answer isn’t just the purchase price — it’s the total cost of owning and living in one, over a decade. The purchase is only the first layer. Financing adds a second price on top of it. Land and placement can cost more than the house itself. Setup, annual operating costs, insurance, depreciation, and eventually exit costs all stack on top. This guide adds it all up — not as a price list, but as a stack you can work through layer by layer — so you know the real number before you commit. For the purchase breakdown in detail, see the purchase-cost guide, and for build-specific costs, see the building-cost guide.
The Complete Cost Stack
Think of the total cost as a stack of layers, each of which can change the answer more than the last. The purchase price is the headline number — but only the first layer. Financing cost is often the second-biggest layer, and the one most rarely counted: interest over a long term can add a large share on top of the sticker price. Land and placement is the variable that changes everything: buying land, renting a spot, family land, or a community each produce a very different decade. Setup and hookups — delivery, foundation or piers, utility connections, skirting, steps, and deck — come next, and are easy to forget until delivery day. Ten-year operating costs — utilities, insurance, maintenance, space rent — are the slow drip that can dwarf the purchase over time. And the true decade total is the sum of all of them, minus whatever value remains at the end. Still far below conventional housing in most comparisons — but honest, because it counts every layer.
Purchase Prices in Brief — the Purchase Guide Carries the Detail
Purchase prices split by route: a DIY build in materials, a builder’s turnkey home, a custom build with bespoke design and premium finishes, a used home where depreciation works in the buyer’s favour, and a factory prefab delivered. Each route’s price range, and what drives it, is covered in full in the purchase-cost guide’s overview — this post takes the purchase price as the first layer of the stack and moves on to the layers that guide does not total.
Financing: The Hidden Second Price, in Brief
Cash is the gold standard: no interest, maximum negotiating power, total cost equal to the sticker price. Every borrowed route adds a second price on top of it, and the shape of that second price depends on the loan type, the rate, and above all the term — longer terms and higher rates add far more than most buyers expect, and short terms with larger down payments are consistently the cheapest financing strategy. The purchase-cost guide’s financing section and the financing guide walk through every loan type and what each costs in shape; this post counts financing as the stack’s second layer and moves on.
Land and Placement: The Deciding Cost
Buying land varies more by region than any other layer in the stack, and in expensive regions it can exceed the house cost entirely — the cheapest tiny house on expensive land is expensive housing. Renting a spot produces a very different decade: a monthly rent, multiplied over ten years, can cost more than the house itself, which surprises most buyers. Family land is the game-changer where it is available: it can eliminate the biggest cost layer entirely, though it brings its own questions about permission, services, and long-term standing. Communities charge a premium for amenities and legal certainty, and that premium buys peace of mind as much as a place to stand.
The land decision framework is simple to state and hard to follow: if land costs exceed the house cost, reconsider the location or the plan. Secure placement before buying the house where you can — placement dictates the economics more than the house price, and a house bought before its place is secured is a house whose biggest cost is still unknown.
Setup and One-Time Costs
Delivery by professional transport, with distance, size, and permits driving the price. Foundation or piers — concrete piers, slab, or helical piles depending on code and soil. Utility hookups — well, septic, or municipal connections — the most variable cost in the stack, because it depends entirely on the site. Skirting, steps, and deck: the finishing touches that make a home on wheels feel like a home. Permits and fees, minimal for a home treated as an RV and substantial for a permitted accessory dwelling. Budget setup alongside the purchase, not after it: it is a layer of the stack, not an afterthought, and getting real quotes for it is the single most useful costing exercise before delivery day.
Annual Operating Costs in Brief — the Monthly Guide Carries the Detail
Utilities, insurance, maintenance, and property tax make up the annual operating layer. Tiny houses sip utilities compared with conventional homes, insurance depends on whether the home is on wheels or on a foundation, maintenance covers roof, heating and cooling service, exterior upkeep, and trailer maintenance for homes on wheels, and property tax is minimal for homes treated as personal property and modest for foundation builds. The monthly-living guide carries the month-by-month detail; this post counts the annual layer and multiplies it across the decade.
10-Year Total Cost Scenarios
Three scenarios show how the stack behaves. The lean scenario: a cash DIY build on family land, with modest setup and careful operating costs — the tiny house dream, fully realised, and the lowest decade total by a wide margin. The typical scenario: a builder house, partly financed, on a rented spot, with ordinary operating costs — comfortable, realistic, and still cheap against conventional housing. The premium scenario: a custom build, financed, on purchased land, with fuller operating costs — expensive tiny living, but on owned land with the equity that brings.
Against conventional housing over the same decade, the lean and typical scenarios win decisively, and even the premium scenario competes — while leaving the owner with a house and, in the premium case, land. The tiny advantage is real but not automatic; choices determine it, and the choices that matter most are land and financing, not the house itself.
Cost Per Year of Housing
The useful metric is the decade total divided by ten: the cost per year of housing. What it reveals is that the lean and typical scenarios beat conventional housing decisively on that metric, while the premium scenario roughly ties — but builds equity in land. The tiny advantage is real but not automatic; choices determine it, and the metric is honest only when every layer of the stack is in the numerator.
Where People Overspend — the Purchase Guide Carries the Traps
The overspends repeat: too much house for the household, too much land cost for the spot, financing badly by term rather than by rate alone, upgrade creep option by option, ignoring operating costs while chasing a low sticker price, and paying for speed in delivery and permits. The purchase-cost guide’s cost-traps section covers each trap in full; this post’s point is narrower — every one of these traps is a layer of the stack left uncounted, and the stack is the defence against all of them.
Maximizing Value: The Smart-Money Playbook
Buy used, pay cash: A used tiny house bought outright on affordable land is the value apex — minimal depreciation remaining, zero interest.
Secure cheap placement first: Before buying the house, lock in where it lives. Placement dictates the economics more than the house price.
DIY the finish: Saves real money and builds sweat equity. Buy a builder shell, finish interiors yourself.
Think in decades: A premium for quality construction pays back in lower maintenance and longer life. Cheap houses are expensive; quality houses are cheap.
Tiny House Costs vs. Other Housing
Against renting: a decade of rent leaves you with no equity, while even the typical tiny scenario leaves you owning a house and possibly land. Against a condo: a decade of condo costs, with association fees on top, easily exceeds the tiny scenarios. Against van or RV life: similar decade totals, but tiny houses offer real-home comfort, better insulation, and stronger community options. In every comparison, the honest basis is the decade total, not the sticker price — and on that basis the tiny scenarios win in almost every comparison.
Depreciation: The Silent Cost
Homes on wheels lose value like vehicles: steeply in the first year, then more slowly, slowing further with age. That lost value over a decade is a real cost — an invisible annual expense, and the price of mobility. It is also the reason buying used is so smart: let the first owner absorb the steepest depreciation. Quality builders, documented maintenance, recognised certification, and tasteful (not bizarre) customisations all slow value loss, and a well-kept older tiny house from a known builder still commands real money.
The foundation exception matters: tiny houses on permanent foundations with owned land don’t depreciate like homes on wheels — they track local real estate. The structure may age, but land value typically rises, and that changes the decade total fundamentally.
Insurance: The Decade-Long Bill
Insurance over a decade is not trivial — a substantial share of the house’s purchase price, spread across ten years. What is covered: structure, contents, liability, and (for homes on wheels) transport coverage. Read exclusions carefully — flood, earthquake, and “vacancy” clauses surprise owners. Saving on insurance: higher deductibles save money, security systems and fire suppression earn discounts, and shopping around every few years pays — specialty insurers for homes on wheels compete hard for the business.
Exit Costs: Selling Your Tiny House
When you sell: listing fees or marketplace commissions, transport to the buyer if you deliver, and repairs to make the home show-ready. Budget a share of the sale price in exit costs, and price against comparable sold listings, not aspirational asking prices — well-priced tiny houses sell in a matter of months, while overpriced ones sit far longer.
Tax on sale: homes on wheels are personal property — sales are generally not taxed as real estate, but gains can be taxable income. Foundation homes get normal real estate treatment including capital gains rules. Consult a tax professional for your situation.
Build Your Number: The Tiny House Cost Worksheet
Step 1 — Purchase: Write your realistic purchase price (new, used, or DIY materials). Add a contingency allowance.
Step 2 — Financing: If borrowing, calculate total interest over the full term (use an online amortization calculator). Add it — this is part of the price.
Step 3 — Placement: Land purchase price OR monthly rent × the number of months in your horizon (120 for a decade). This is usually the biggest line — don’t skip it.
Step 4 — Setup: Delivery, foundation, hookups, permits. Get real quotes; this varies more than any other category.
Step 5 — Operating × 10: Annual utilities + insurance + maintenance + taxes, times 10. Be honest, not optimistic.
Step 6 — Subtract residual value: Estimated sale value at year 10 (depreciated for THOWs, appreciated for foundation + land). This is your net 10-year cost — the number that matters. Compare it against 10 years of your current rent to see the true savings.
The Intangibles: What the Spreadsheet Misses
Time wealth: Lower housing costs can buy something money usually can’t: time. Tiny dwellers working shorter weeks aren’t just saving money — they’re buying back thousands of hours. Price that at any hourly rate and the tiny advantage doubles.
Stress and health: The financial peace of a low monthly housing cost versus a conventional one has real, if unpriced, health value. Housing cost stress is a documented health burden — linked to sleep loss, anxiety, and chronic disease.
Optionality: Low fixed costs create freedom to take risks: start a business, change careers, travel, or weather a job loss without panic. This option value never appears in cost comparisons, but owners consistently cite it as the biggest benefit.
The honest accounting: Run the numbers — the tiny house wins on math alone. But the intangibles are why people stay: the spreadsheet justifies the decision, but freedom is why they made it.
Frequently Asked Questions
What is the total cost of owning a tiny house?
The decade total, all-in (purchase, financing, land, setup, operating), versus a substantially higher decade total for conventional housing over the same period. The exact number depends mostly on land and financing choices — work through the stack above for your own number.
Are tiny houses cheaper than regular houses?
Yes, typically much cheaper over a decade. Purchase prices are a fraction of conventional homes, and operating costs run well below. The savings are largest with cash purchases and affordable land.
What costs the most in tiny house living?
Over ten years: land and placement usually exceeds the house purchase itself, followed by financing interest, then operating costs. The house sticker price is often only the third-biggest cost — which surprises most buyers.
How can I keep tiny house costs down?
Buy used or DIY, pay cash (or finance short), secure affordable placement before buying, and maintain the home yourself. Each of these saves substantially over a decade.
Do tiny houses appreciate?
Homes on wheels depreciate like vehicles. Foundation tiny houses on owned land typically appreciate with the land. For investment purposes, the land matters more than the house.
Final Considerations
How much do tiny houses cost? The sticker gives one number, but the honest decade answer is the whole stack: affordable purchase, minimal interest, sane land costs, and tiny operating bills, sustained for years — minus whatever value remains at the end. That total still beats conventional housing by a wide margin, and the lean scenarios beat it by life-changing amounts. The secret isn’t the small house; it’s the small total. Price the whole stack before you buy, optimise the big layers (land and financing first), and revisit your numbers annually — costs drift, and the owners who stay ahead are the ones who keep score. Let the tiny house do what it does best — turn housing from your biggest expense into your biggest advantage.

5 Comments