
Trading a salary for a homestead without a financial plan is how dreams become distress sales. Freedom has a budget, and the numbers are kinder than most people fear but stricter than most people hope. This guide breaks down the income streams, the expense categories and the math of financial independence off-grid — how to find your freedom number, dodge the money traps, and build a budget that holds.
1. Homesteading Economics at a Glance
Homesteading economics is not about getting rich — it is about needing little. The homestead inverts the consumer equation: instead of raising income to cover an ever-growing burn rate, you cut the burn rate, build producing assets, and let time do the compounding. Financial independence off-grid is a spreadsheet before it is a lifestyle: a tracked annual spend, a freedom number derived from it, three big expense categories driven down, several income streams fitted to the land, and zero consumer debt while it all comes together. The table below gathers the whole system in one place; the sections after it take each layer apart in turn.
| Attribute | Detail |
|---|---|
| The Burn Rate | The tracked annual spend — a homestead typically runs $20,000–40,000 a year, frugal to comfortable, with no mortgage |
| The Freedom Number | The annual spend × 25 — the 25× rule, the 4% rule’s cousin, is the invested target |
| The Leverage | Halving the burn halves the number needed — $30,000 of spend becomes $15,000, and freedom arrives twice as fast |
| Housing | The paid-off tiny home — rent and mortgage eliminated, the biggest single cut of all |
| Transport | The e-bike plus one car — retiring the second car saves $7,000 a year |
| Food | The garden and the preserved harvest — a 30–50% cut in the food bill |
| The Big Three Total | $15,000–25,000 a year freed across housing, transport and food — the foundation of the whole plan |
| Farm Income | The market garden — $5,000–20,000 a year from eggs and produce, the secondary stream |
| The Producing Assets | Solar paying a $0 electric bill across a 25-year life; repair and build skills worth $100 an hour saved |
| The Timeline | 3–7 years across four phases — cutting, land, building, income — with zero consumer debt throughout |
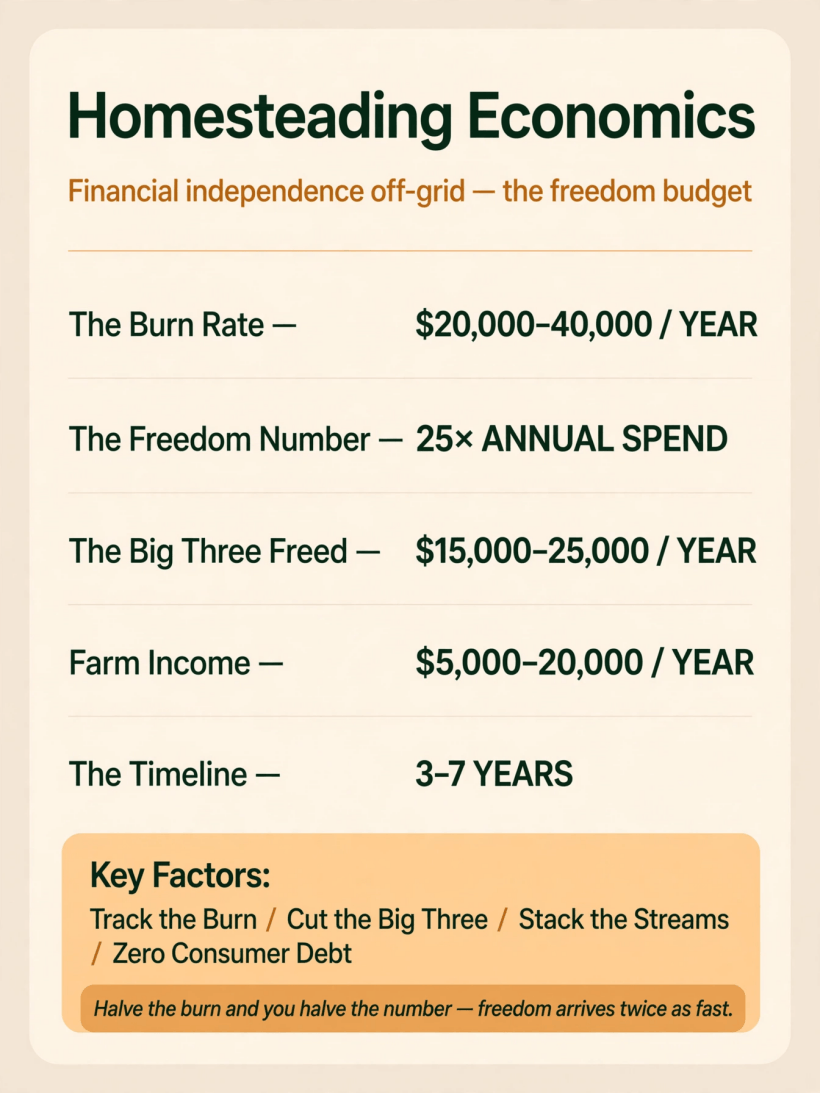
A $20,000–40,000 burn rate, a freedom number of 25×, and $15,000–25,000 a year freed by the big three — the whole system on one card.
Read the table as a sequence rather than a shopping list. The burn rate comes first because everything else is derived from it: the freedom number is just the burn multiplied, the big three are where the burn is cut, and the income streams only have to cover what the cutting leaves behind. A household that skips the tracking and guesses at its number builds the whole plan on sand. A household that knows its real costs — honestly, over a full 12 months — can plan the transition in phases and watch each one land.
2. The Burn Rate: Knowing Your Number
Everything starts with the number: the annual spend, tracked honestly over 12 months. Not the aspirational spend, not the spend of a good month — the real one, with the irregular bills, the repairs and the small leaks included. The typical homestead lands between $20,000 and $40,000 a year, running from the frugal end to the comfortable one, and the range assumes the decisive condition: no mortgage. That figure is the burn rate, and it is the single most important number in the entire plan, because the freedom number is built directly on top of it.
From the burn rate, the math is almost disappointingly simple: multiply by 25. The 25× rule — the 4% rule’s cousin — turns an annual spend into the invested sum that can carry it. Spend $30,000 a year and the number is $750,000; that arithmetic is exactly why the cutting matters more than the earning. Halve the burn to $15,000 and the needed sum halves with it. Every dollar removed from the annual spend removes twenty-five dollars from the target — the freedom’s leverage, and the reason this guide works the expense side of the ledger before it ever touches income.
The tracking itself deserves respect as a phase, not a chore to rush. Twelve months is the honest unit because homestead spending is seasonal: the heating month, the preserving month, the repair that only happens once a year all hide from a shorter sample. A household that tracks for a single quarter will understate its burn, understate its freedom number by twenty-five times the error, and build the transition on the gap. The tracked year is also where the leaks confess themselves — the small recurring charges and habits that no one remembers approving, which are often the easiest dollars in the whole burn rate to remove.
3. Cutting the Big Three: Housing, Transport, Food
Budgets are not cut evenly; they are cut where the weight is. Housing is the largest category in almost every household, and the homestead answer is elimination rather than reduction: the paid-off tiny home, owned outright, with no rent and no mortgage leaving the account each month. It is the biggest single move in the whole system, and it is what makes the $20,000–40,000 burn range possible at all. A household still carrying a housing payment is running a different, heavier math than everything in this guide assumes.
Transport is the second cut, and its shape is the micro fleet: the e-bike for daily miles plus one car kept for what a car is genuinely needed for. Retiring the second car — the second car’s funeral, in the original’s phrase — saves $7,000 a year in payments, insurance, fuel and maintenance that simply stop existing. The riding side of that swap, from battery sizing to safety gear, is covered in e-bike commuting 101. Food is the third cut, and uniquely it is a cut that produces: the garden plus the preserved harvest trims 30–50% off the food bill while feeding the household better. Together the big three free $15,000–25,000 a year — the foundation the rest of the plan stands on.
4. Income: The Homestead Streams
With the burn cut, the income side has a smaller target to hit — and the homestead hits it with a stack of streams rather than a single salary. The primary stream, for most households making the transition, is remote work: the salary’s portability, carried onto the land over an internet connection. It is the bridge income that funds the building years and, for many, simply continues. The full treatment of connections that work in the wilderness is the guide to off-grid internet and staying connected — the stream is only as reliable as the link underneath it.
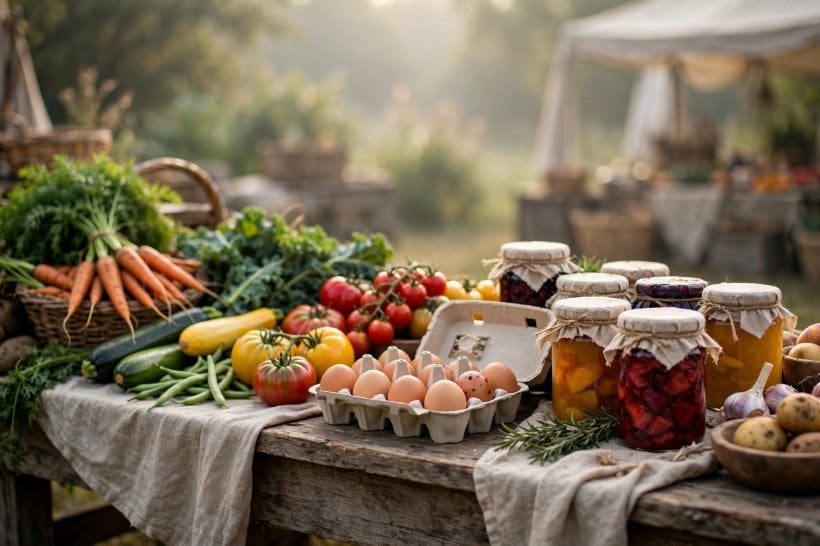
The secondary stream is the farm itself: the market garden, worth $5,000–20,000 a year from eggs and produce — real money, though seasonal and weather-exposed in a way a salary is not. Beyond it sit two slower-built streams. Digital income — content and courses — is the scalable one, leveraged rather than hourly, but slow to build and honest about it. Crafts are the artisanal stream: woodwork and other value-added goods sold at the farmers market, turning skill and offcuts into margin. No single stream has to carry the whole burn rate; that is the point of the stack. Each covers part, each fails differently, and the household’s income stops depending on any one of them surviving.
5. The Producing Assets: Land and Systems
Money saved is only half the inversion; the other half is assets that produce. Land is the first: bought well and held, it appreciates while it carries everything else — the roof, the garden, the systems. Solar is the second, and its return is best read as a dividend: a $0 electric bill, month after month, across the system’s 25-year life. The household stops renting its power and starts owning the means of it. Which source should generate that power on a given property is the comparison worked through in solar versus wind power for the homestead.
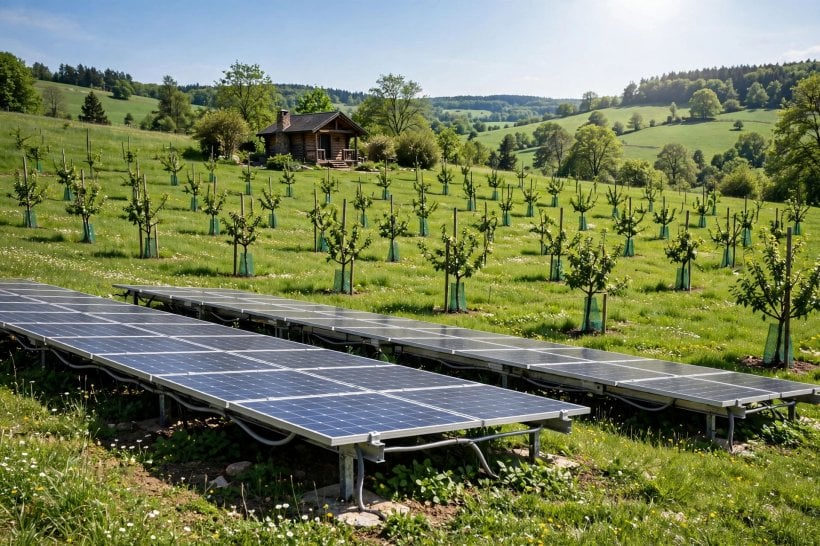
The garden and orchard are the food factory: planted once, they compound — perennials especially, returning more each year for the same ground. Water and power systems belong in the same ledger: the catchment sizing behind rainwater harvesting systems turns rainfall into supply, and a stream on the land opens the option in micro-hydro power from small streams. Last and most portable are skills — the ultimate producing asset. Every repair done and thing built at home is money not paid out; the original prices the habit at $100 an hour saved, and unlike the other assets, skills cannot be repossessed, flooded or sold out from under you.
6. Debt: The Freedom Killer
One rule sits above the phases and the streams, stated as a commandment: zero consumer debt. The math is the interest’s theft. A balance carried at 20% APR is a freedom tax — money leaving every month to buy nothing, while the same dollars could be cutting the burn or building an asset. A homestead budget has no slack for that leak; the whole plan runs on a burn rate low enough that a 20% headwind quietly cancels the big three’s gains. Cash, not credit, is the operating medium: if it cannot be bought outright, it waits.
Land is the one careful exception, and even there the terms are strict: owner-financed where possible, on a short schedule, paid fast. The distinction is between debt that buys a producing asset on disciplined terms and debt that buys consumption at punitive ones. The first is a tool with an end date; the second is a treadmill. Households making the transition treat the order as fixed: consumer balances are extinguished before the land phase begins, because every month of 20% APR interest is a month added to the 3–7 year timeline — the interest does not merely cost money, it costs years of the life the move was for.
7. The Transition: Four Phases Over 3–7 Years
The transition is phased because each stage funds and de-risks the next. Phase 1 is the cutting: 12 months of tracking the burn rate honestly while halving it — the big three attacked in place, before any land is bought, so the household learns its real number and banks the difference. Phase 2 is the land: bought right, using the scoring discipline — a property scoring 70+ on the system — rather than bought emotionally. That method is set out in the guide to where to buy land for eco-living, scored out of 100 points.
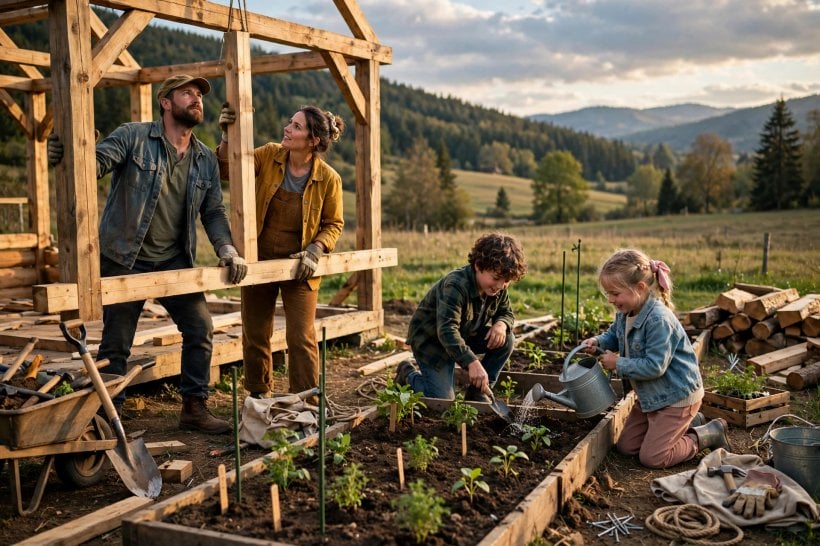
Phase 3 is the building: the systems go in — solar, water, garden — the producing assets that lower the burn further and start returning value. Phase 4 is the income: the streams assembled and diversified, remote work joined by the farm and the slower digital and craft income as the land begins to pay its share. The whole arc runs 3–7 years for the typical household — the patient timeline, and the worth-it one. The phasing is what makes it survivable: at no point does the household bet everything on a single season, and at every point it can pause, hold position, and resume when the budget allows.
8. The Mindset: Enough
The last component is not arithmetic, and without it the arithmetic does not hold. Enough has to be defined: a known number, a stated standard, a point at which the household is satisfied rather than merely paused. The definition is what turns the freedom number from a target into a finish line — without it, the goalposts move with every raise and every advertisement, and no burn rate is ever low enough. Comparison is the enemy and is rejected on sight: the neighbor’s truck is irrelevant, a data point about someone else’s budget, not evidence about yours.
Underneath sits the revaluation of wealth itself: time is the true currency, and the hours are the riches. The paradox the original names is the whole philosophy in one line — the less you need, the richer you are. A household that needs $20,000 a year owns its calendar in a way a household needing three times that cannot, whatever either earns. That is also why choosing the place matters as much as choosing the numbers: the community side of the match is worked through in the eco-friendly city match quiz, because a low burn rate in the wrong place is its own kind of expense.
9. Resilience: Building the Budget That Bends
A budget balanced to the dollar is a budget one bad season from breaking, and the original’s framing insists on resilience built in from the start. The first layer is the stream stack itself: remote work, farm income, digital and crafts fail in different ways and different seasons, so the household’s income dips rather than vanishes when one line falters. The second layer is the producing assets — a garden, an orchard and a power system keep delivering through a cash-flow squeeze, lowering the burn precisely when money is tightest.
The third layer is skill, again: the household that can repair, build and preserve can convert time into savings on demand, at that $100-an-hour rate, which makes its effective burn rate elastic in a way a purely purchasing household’s never is. Even the e-bike at the centre of the transport cut can be kept independent of fuel prices and grid power alike, charged from the homestead’s own array by the method in the guide to charging an electric bike with off-grid solar power. Resilience, assembled this way, is not a separate savings product; it is what the whole structure — cut burn, stacked streams, producing assets, no debt — adds up to when a bad year tests it.
10. Reading the Whole Ledger: How the Pieces Compound
Step back and the system is a single loop. The tracked burn rate sets the freedom number at 25×. Cutting the big three — $15,000–25,000 a year across housing, transport and food — shrinks that number faster than saving alone ever could. The streams cover what remains, the producing assets lower the burn a little more each year as the orchard matures and the systems bed in, and zero consumer debt keeps the 20% leak plugged throughout. Each element makes the others easier: that is what the compounding in the introduction actually refers to.
The discipline that holds the loop together is measurement. The household that tracks for 12 months before moving, phases the transition over 3–7 years, and re-reads its own ledger honestly can see every lever’s effect in its own numbers rather than in anyone’s promises. Nothing in the system requires an exceptional income, an exceptional property or an exceptional climate — it requires the sequence: know the number, cut the big three, buy producing assets, stack the streams, refuse the debt, define enough. Run in that order, the budget stops being the obstacle to the homestead and becomes the mechanism that delivers it.
It is worth naming what the system is not. It is not a promise that the land pays for itself in year one — the farm stream’s $5,000–20,000 range and the slow build of digital income are stated plainly in the original because they are true. It is not a bet on any single asset, any single stream or any single season going right. And it is not austerity as an identity: the comfortable end of the burn range, $40,000 a year, is a legitimate target for a household that would rather take an extra year or two of transition than live the frugal end forever. The economics flex; the sequence does not.
Final Considerations
Know your number — the tracked burn, honestly counted over 12 months. Kill the big three: housing, transport and food, worth $15,000–25,000 a year. Build income streams that fit the land — the remote salary first, the farm behind it, the digital and craft income growing slowly. Buy producing assets: the solar array, the orchard, the skills. Carry zero consumer debt — the commandment. And define enough, because the paradox holds: the less you need, the richer you are. Financial independence off-grid isn’t wealth. It’s the freedom budget, balanced.

3 Comments